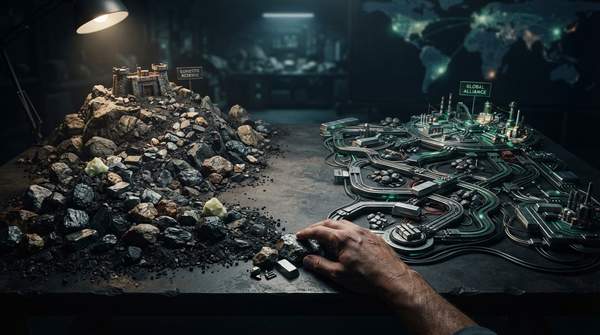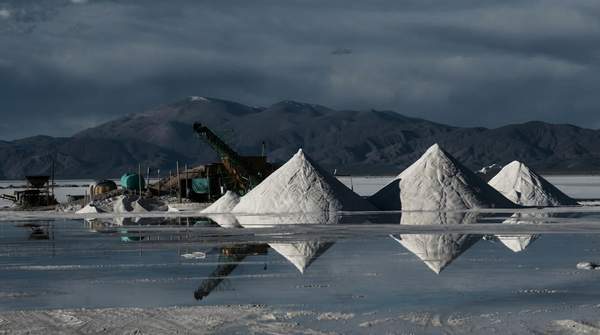
Critical mineral supply chains can be diversified through four distinct strategic pillars, as defined by the U.S. Department of Energy: diversifying supplies, developing material alternatives, improving manufacturing efficiency, and investing in recycling and reuse. Each pillar attacks concentration risk through a different mechanism, and each carries its own trade-offs in speed, cost, and exposure to geopolitical friction. This article compares all four side by side and examines the specific policy tools—multilateral partnerships, coordinated tariffs, and subsidies—used to implement the most common of them.
Introduction: The Imperative for Critical Mineral Diversification
The stakes are concrete. The Department of Energy's critical minerals and materials portfolio spans rare earth elements used in electric vehicle motors; lithium, cobalt, and high-purity nickel used in energy storage; platinum group metals used in automotive, chemical, fuel cell, and hydrogen catalysts; and gallium and germanium used in semiconductors. Concentration in these supply chains is widely viewed as a security vulnerability: Resources for the Future notes that many observers believe targeted restrictions on critical minerals could cause major economic dislocations and threaten national security, and that this potential for geopolitical conflict underlies the need to geographically diversify supply chains. The DOE framework treats diversification not as a single lever but as four complementary pillars, supported by cross-cutting functions including analysis and advanced tools, market assessment and development, international engagement and standards, and education and workforce development.
Strategy 1: Diversifying Foreign Supplies
The first pillar focuses on securing critical minerals from a broader range of international sources rather than concentrated ones. Its mechanisms are largely governmental: multilateral coalitions such as the Forum on Resource Geostrategic Engagement (FORGE), a multilateral effort to counter Chinese dominance in critical mineral supply chains; coordinated variable tariffs; loosely coordinated subsidies; and fiscal incentives and industrial policy tools.
The European Union offers a working illustration of this approach in practice: its 2020 Action Plan on Critical Raw Materials and the 2024 Critical Raw Materials Act established a framework to reduce dependencies through domestic production and refining alongside international partnerships, with ODI reporting modest diversification of supply and incremental gains in domestic capacity for minerals such as nickel and helium, plus new cooperation instruments including Clean Trade and Investment Partnerships. The trade-off is that this strategy depends heavily on international coordination and can invite countermeasures from the dominant supplier it is designed to offset.
Strategy 2: Developing Material Alternatives
The second pillar aims to reduce demand for specific critical minerals by researching and developing substitute materials for their applications. This is a long-term approach: rather than shifting where minerals come from, it changes what products are made of. The Department of Energy supports this work through research, development, demonstration, and deployment efforts—activities intended to foster innovation in materials science, supported by cross-cutting functions such as analysis and advanced tools and market assessment. The benefit is potential technological independence from a constrained input altogether; the cost is time and uncertainty, since substitution requires sustained innovation investment before it can relieve a supply concentration that may already be causing price or availability stress.
Strategy 3: Improving Manufacturing Efficiency
The third pillar works on the demand side in a different way: reducing the amount of critical minerals required in manufacturing processes, optimizing resource use and minimizing waste. Like the alternatives pillar, it is supported by the Department of Energy's enabling activities—advanced analytical tools, market assessment and development, and international engagement and standards—which the agency describes as cross-cutting functions to enhance research and deployment across its strategy. Efficiency improvements can deliver gains without waiting for new mines or new materials to come online, making them comparatively fast where process changes are feasible. The limitation is scope: efficiency reduces intensity of use but does not eliminate dependence on the underlying mineral, so it complements rather than replaces sourcing or substitution strategies.
Strategy 4: Investing in Recycling and Reuse
The fourth pillar promotes a circular economy for critical minerals by increasing recycling and reuse rates, with the aim of creating domestic secondary sources of critical materials. Its distinctive advantage is geographic: recovered material is, by definition, already inside the consuming economy, insulating supply from export restrictions abroad. The Department of Energy's portfolio includes work on battery critical materials supply chain challenges and opportunities, drawing on its 2020 Request for Information and workshop results, alongside criticality assessments that update previous DOE reports based on recent market and technological developments. The trade-off is that secondary supply depends on the volume and timing of end-of-life products flowing back—a constraint that lags primary demand growth, particularly in fast-expanding applications like energy storage.
Comparative Framework: Critical Mineral Diversification Strategies
The table below compares the four pillars across their mechanisms, challenges, and benefits, so readers can align a strategy with a specific policy goal such as speed of implementation, cost-efficiency, or long-term technological independence.
| Strategy | Mechanism / Key Actions | Challenges and Risks | Potential Benefits |
|---|---|---|---|
| Diversifying foreign supplies | Multilateral partnerships such as FORGE; coordinated variable tariffs; loosely coordinated subsidies; fiscal incentives and industrial policy supporting alternative supply hubs | Geopolitical competition; potential Chinese retaliation against large, visible trade measures; difficulty coordinating subsidies across coalition members; uncertain project finance without credible demand signals | Clear, consistent signals for geographically diversifying supplies; new international cooperation instruments; reduced reliance on concentrated sources |
| Developing material alternatives | Research, development, demonstration, and deployment of substitute materials, supported by DOE enabling activities | Long development timelines; innovation outcomes are uncertain before substitution relieves supply stress | Long-term reduction in demand for specific critical minerals; technological independence from constrained inputs |
| Improving manufacturing efficiency | Advanced tools, market assessment, and international engagement to reduce critical mineral intensity in manufacturing | Reduces use but does not eliminate dependence on the underlying mineral; process change feasibility varies | Optimized resource use and minimized waste; gains possible without new mines or new materials |
| Investing in recycling and reuse | Circular-economy approaches raising recycling and reuse rates, informed by DOE battery supply chain workshops and criticality assessments | Secondary supply depends on end-of-life product volumes, which lag primary demand growth | Domestic secondary sources of critical materials insulated from foreign export restrictions |
Read side by side, the pillars are not mutually exclusive. The Department of Energy presents them as distinct strategic options but supports all four through the same cross-cutting functions, suggesting an integrated approach in which, for example, recycling builds domestic supply while alternatives and efficiency reduce demand for it.
Policy Tools for Diversifying Supplies: Partnerships, Tariffs, and Subsidies
Because diversifying supplies is the most internationally exposed pillar, its tools deserve closer scrutiny. Resources for the Future's analysis of FORGE and related instruments weighs two main options. A coordinated variable tariff could provide clear and consistent signals for geographically diversifying supplies in critical mineral markets, but it would require extensive within-coalition information exchange and monitoring, mechanisms to manage disputes over national industrial policies, and would remain a visible target—Chinese retaliation against such a large and visible trade measure is a stated concern.
Loosely coordinated subsidies present the mirror-image trade-off: they may be harder to coordinate, less efficient, and less transparent than price floors, but they could provide basic reassurance about supply while reducing retaliation risks and internal political opposition to higher domestic mineral prices, and could be focused on priority critical minerals exploiting comparative advantages within the coalition. A stakeholder-driven initiative convened by the Geneva Graduate Institute's Centre for Trade and Economic Integration points to a further toolkit—fiscal incentives, industrial policy, co-financing strategies, and market-making mechanisms—to help countries invest in alternative supply hubs and strengthen upstream and midstream capabilities.
ODI adds a financing caveat: without credible demand signals such as price floors or long-term procurement commitments, it remains uncertain how effectively project finance can be mobilized, particularly where strategic competitors may seek to undermine commercial project viability.
Strategic Choices for Resilient Critical Mineral Supply Chains
Policymakers and industry stakeholders should evaluate critical mineral diversification strategies based on their specific objectives, considering the trade-offs between immediate supply security, long-term technological independence, and resource efficiency. The evidence supports a portfolio logic: diversifying supplies addresses concentration fastest but carries the highest coordination and retaliation risks; alternatives and efficiency reduce exposure over time; recycling converts existing domestic stocks into supply. The observable signal will be the adoption of integrated policy frameworks that combine elements from multiple diversification strategies, alongside measurable improvements in supply chain resilience metrics such as reduced import reliance or increased domestic processing capacity for critical minerals.
Sources
- Critical Minerals and Materials — Energy.gov
- Critical Mineral Policies for Supply Chain Diversification and Price Hedging — Resources for the Future
- Critical minerals geopolitics in 2026: risks, supply chains and global power shifts — ODI: Think change