Most corporate climate disclosures tell you what a company is doing, not what is happening to the environment. Headline ESG metrics frequently reward self-reported checklists, standalone carbon footprints and vague ambitions, while the emissions-heavy subsidiaries, unaudited data and quietly shifted baselines stay out of view. For an investor, that gap is a pricing problem: it hides climate risk inside otherwise ordinary securities. The fix is not more data but better scrutiny, and it can be reduced to four diagnostic questions.
The Illusion of Climate Progress: Why Current Metrics Fall Short
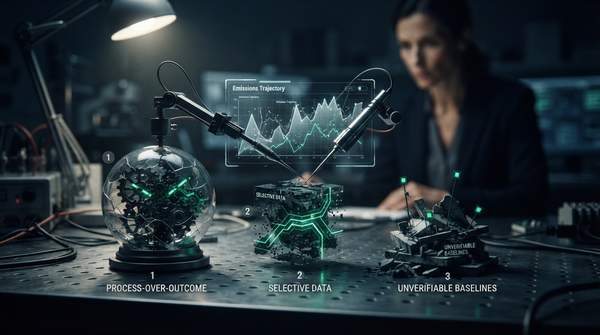
The pattern is well documented. Reporting on environmental, social and governance performance, in the words of one analysis of Indian climate metrics published by ESG News.earth, tends to prioritize "self-reported checklists over verifiable environmental improvements." The same reporting cites a stark illustration: the Swachh Vayu Survekshan, a municipal evaluation, allocates over 60% of its total weightage to process activities such as mechanical street sweeping and road paving. The Indian Institute of Science consequently found Lucknow scoring 198 out of 200 nationally even as peak winter air quality index readings soared past 374.
Corporate reporting shows the same structural weakness. Research by the CFA Institute, cited in the same article, found that 76% of listed entities report climate metrics strictly on a standalone basis, meaning parent companies disclose low carbon footprints while unlisted subsidiaries run emissions-heavy industrial operations outside public view. The lesson transfers directly to investing: a metric can be accurate, audited and still misleading, if it measures the wrong thing or covers the wrong boundary.